VWAP in Gold Futures
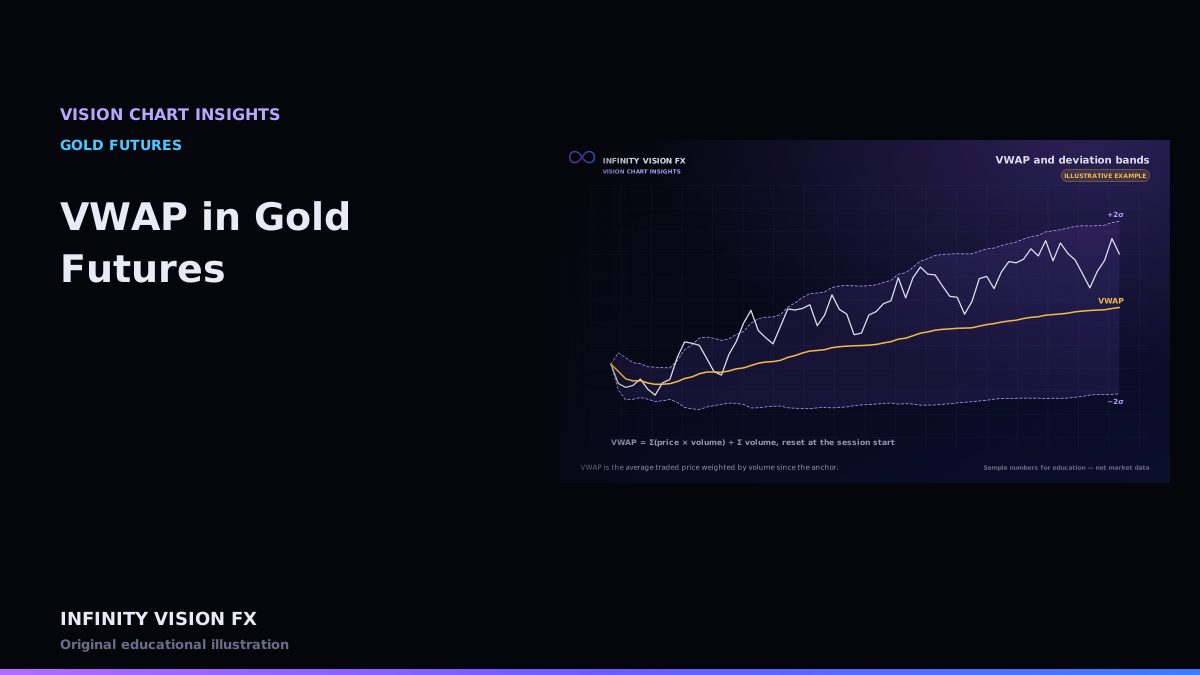
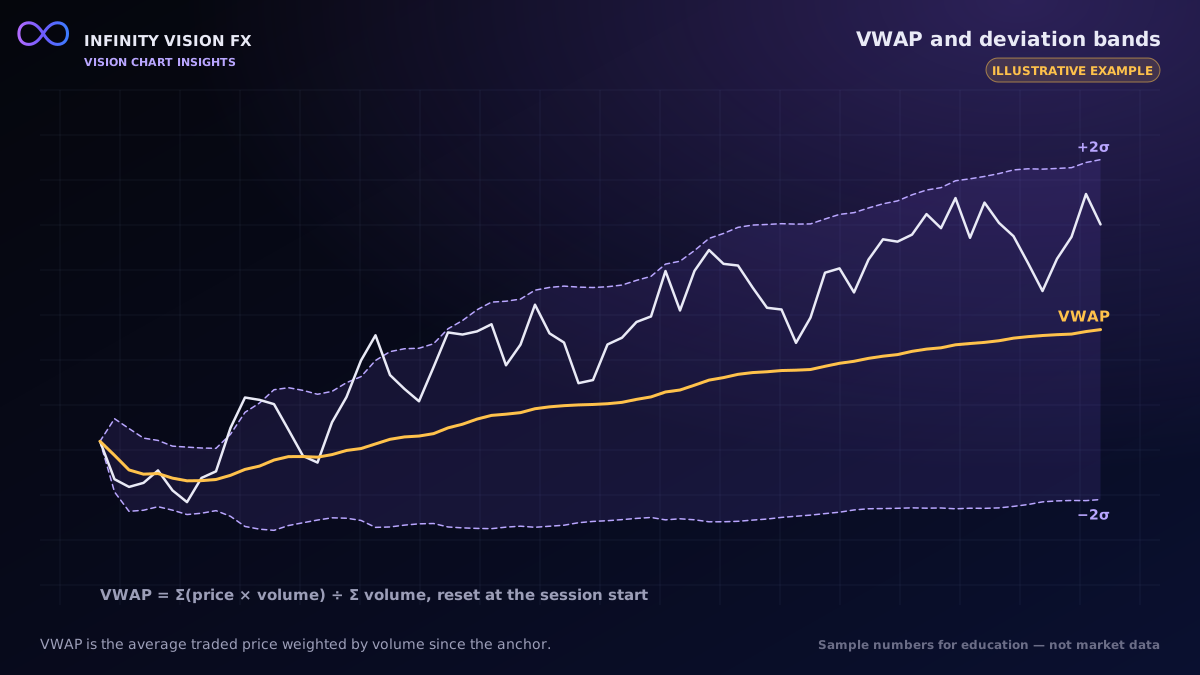
VWAP — volume-weighted average price — is the average price paid during a period, where each trade counts in proportion to its size.
The formula
VWAP = Σ(price × size) ÷ Σ size, accumulated from the anchor point.
Deviation bands use the volume-weighted standard deviation:
σ = √( Σ(price² × size) ÷ Σ size − VWAP² ), and bands at VWAP ± 1σ, ± 2σ.
Session boundaries for gold futures
COMEX gold trades on CME Globex nearly 23 hours a day, Sunday to Friday, with a daily break. VISION CHART uses Chicago time:
- Session / daily VWAP — resets at 17:00 Chicago time, the start of the Globex trading day.
- Weekly VWAP — resets at the Sunday evening session start.
- Monthly VWAP — resets at the first session of the month.
- Anchored VWAP — starts from any time you choose, such as a swing low or a news release.
Reading VWAP
- Price holding above session VWAP shows trades on average have happened at lower prices — buyers have, on average, been rewarded so far today.
- Distance from VWAP in σ units measures how stretched price is relative to the session's own trading.
Data requirements
VWAP needs real traded volume at each price. A VWAP calculated from candles with tick volume is an approximation and is labelled as such.
A worked example (illustrative)
Three trades since the session start: 2 contracts at 2400.0, 6 at 2401.0 and 2 at 2402.0.
- Σ(price × size) = 4800 + 14406 + 4804 = 24010
- Σ size = 10 → VWAP = 2401.0
- σ = √(Σ(price² × size) ÷ 10 − 2401.0²) ≈ 0.63 → +1σ band ≈ 2401.63, −1σ ≈ 2400.37
Anchored VWAP
An anchored VWAP starts from a moment you choose — a swing low, the start of a news-driven move, or the high of the week. It answers: "what is the average price paid by everyone who traded since that event?". VISION CHART lets you set the anchor from the chart.
Limitations
VWAP is a description of past trading, updated as new trades arrive. Bands based on standard deviation assume nothing about the future; markets often trade beyond ±2σ during strong moves.
Key takeaways
- VWAP is the size-weighted average traded price since an anchor.
- Gold futures sessions reset at 17:00 Chicago time.
- Bands describe how far price is from that average in standard deviations.
Next article: Footprint Imbalance Explained
Educational content only, not financial advice. Examples and illustrations use sample numbers and are not observations of real market activity. Order flow describes past and present activity; it does not predict prices.